Oil and Treasury yields haven’t moved this closely in seven years. That’s bad news for markets

Oil and Treasury yields haven’t moved this closely in seven years. That’s bad news for markets. NYSEOil prices and Treasury yields are moving in a tight lockstep, compounding the pressure on markets as investors grapple with worries over higher inflation.
What happened
The exceedingly tight relationship means another leg higher in oil could increasingly reverberate across financial markets through higher inflation expectations, elevated Treasury yields and steep borrowing costs, while potentially keeping the Federal Reserve monetary policy tighter for longer, said industry veterans. Oil and 10-year Treasury yields are moving in near lockstep, with their correlation at its strongest since 2019. Higher oil could drive inflation and Treasury yields higher, tightening financial conditions and pressuring stocks and consumers.
Higher Treasury yields reduce the relative appeal of equities as they raise financing costs for businesses, while expensive oil squeezes margins for companies dependent on energy and transportation. Higher energy prices feed directly into gasoline costs and indirectly into goods and services transported by truck and rail, while rising Treasury yields filter into mortgages, auto loans and other borrowing costs, said Andy Lipow, president of Lipow Oil Associates. The one-month rolling correlation between front-month West Texas Intermediate crude and the 10-year Treasury yield has climbed to 0.
The synchronized moves come as oil prices have surged amid the Middle East conflict, pushing the benchmark 10-year Treasury yield to its highest level since 2007.
The wider picture
" "That makes energy headlines more consequential for broader markets and reduces some of the diversification investors would normally expect between commodities and government bonds," he added. "It's certainly bad news that if oil prices continue to move higher, that would indicate that bond yields are moving higher, and then higher inflationary expectations raise the odds that we'll be in a tightening cycle when it comes to the Fed funds rate," Yardeni said. He said technology growth stocks are more vulnerable as interest rates remain elevated. watch nowVIDEO4:1004:10Investors caught between yields, oil and TrumpSquawk Box Europe"You're going to have a bond bear market, the yields headed up, and I don't see anything that stops the upward march of oil and natural gas prices either," said Sri-Kumar.
"Both increase in the WTI crude price, along with the increase in the treasury yield, are bad news for the consumer," Lipow said. For businesses, higher yields also raise the cost of financing inventories and investment, potentially weighing on capital-intensive projects such as the buildout of artificial intelligence and the energy infrastructure needed to support it, Lipow said. While oil and Treasurys have entered a tighter relationship, it may not be so if global tensions recede.
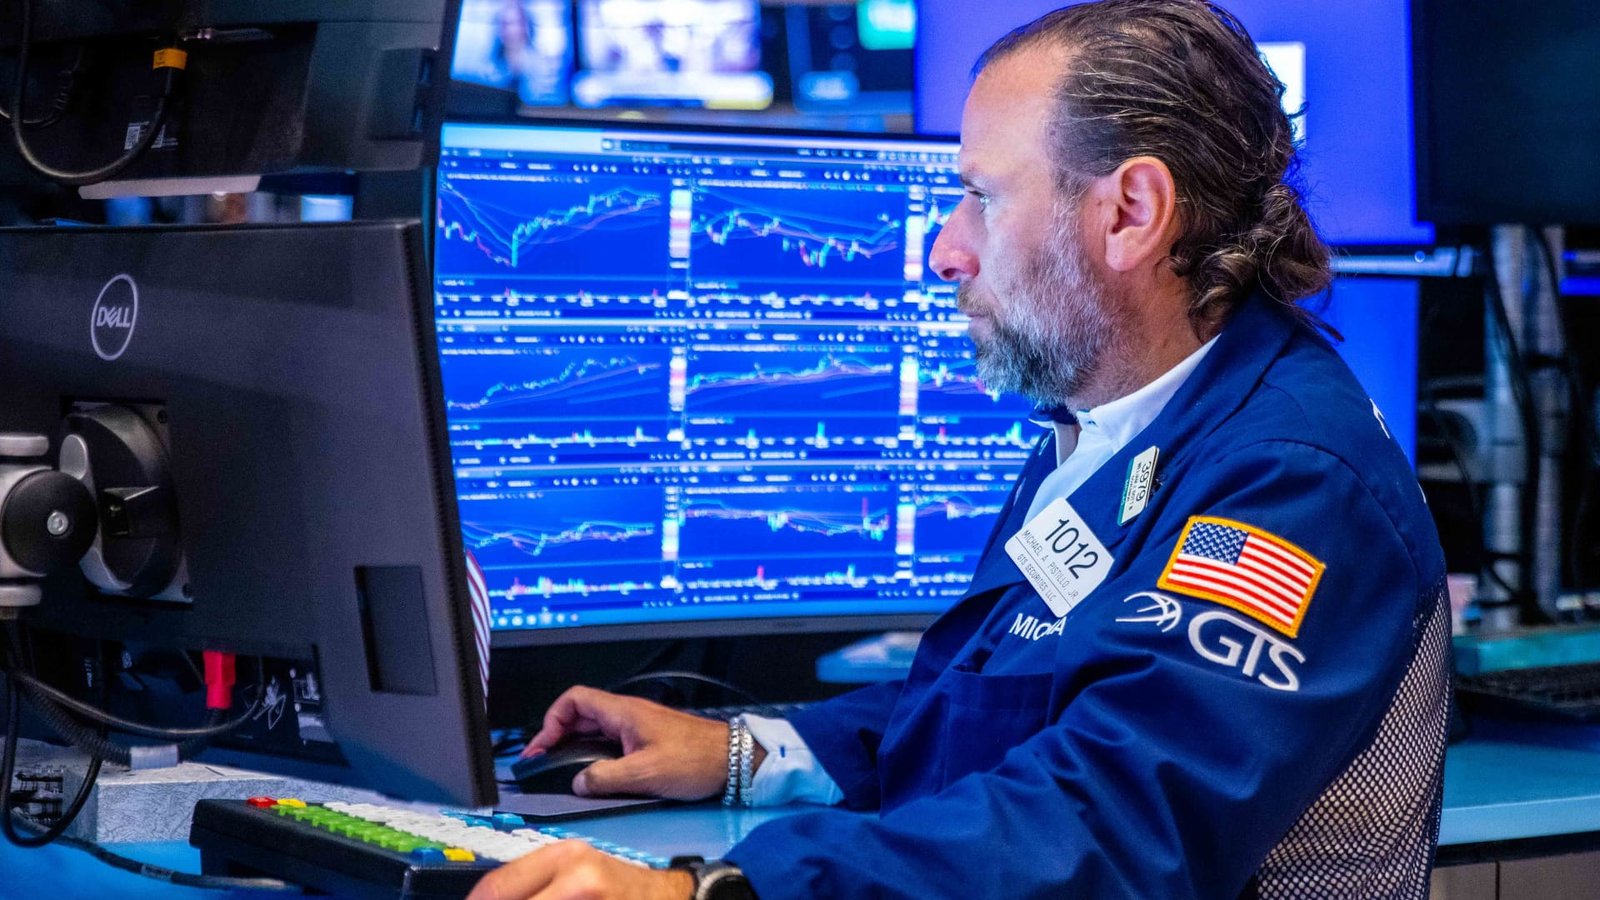
Strategists caution the unusually strong relationship may quickly unwind if geopolitical tensions ease or growth fears intensify. Traders work at the New York Stock Exchange on Aug.
What has been reported
That's the strongest positive relationship since June 2019, and before that October 2014. S. oil prices"The main impact is that an oil shock now transmits more directly into financial conditions," said Billy Leung, investment strategist at Global X ETFs. "Higher crude can lift inflation expectations, delay Fed easing and raise the discount rate applied across equities and credit at the same time. The implications stretch across asset classes. Growth and technology stocks can be particularly exposed because their valuations depend heavily on earnings expected far into the future.
Ed Yardeni, president of Yardeni Research, said the chain increasingly runs from energy through inflation and bonds into monetary policy and equities. "Not one and done, but there there could be two or three rate hikes up ahead here, and that in turn can certainly be unsettling for the stock market. " Komal Sri-Kumar, president of Sri-Kumar Global Strategies, is already steering investors away from assets most vulnerable to higher rates.
What happens next
He favors short-duration fixed income and defensive equities, while recommending physical assets including real estate, copper and gold as hedges. 96 correlation is unusually high but could unwind rapidly if geopolitical tensions ease or growth fears begin to dominate. Lipow similarly said the magnitude partly reflects the relatively short period since the U. Choose CNBC as your preferred source on Google and never miss a moment from the most trusted name in business news.